

Read chapter 7
The whole of chapter seven, free. About 7 min. Turn the pages with the arrows, your keyboard, or a swipe.
Chapter 7
Using Triggers to Build Resilient Money Habits
Every time you feel that “uh-oh” money knot in your body, you’re not just having a thought - you’re getting a trigger. And if you don’t turn that trigger into a habit cue, your plan gets hijacked long before your spreadsheet even has a chance. That’s why resilient money habits aren’t built with willpower. They’re built with signals.
In my world, Avery - 45, runs a small business, and can sell anything to anyone - wasn’t struggling because she didn’t understand money. She understood it too well. Her problem was what happened after a trigger hit: the moment a client delayed payment, or a surprise expense popped up, her body went straight into “fix it now” mode. Then her brain used that urgency as an excuse to abandon the very habits she’d worked hard to set up.
The “Fix-It-Now” Trigger That Wrecks Your Money Habits
Avery recognized the pattern instantly once she knew what to look for. A payment came in late - sometimes by a day, sometimes by a week - and she felt it in her chest like a tight fist. Her inner dialogue didn’t sound calm or rational. It sounded like: We can’t fall behind. Do something. Solve it today. Then she’d start scanning accounts, checking balances again and again, and “temporarily” moving money from savings to cover the gap. “Temporary” always had a way of turning into the new normal.
The wild part? The trigger didn’t need to be massive. It could be small: an unexpected invoice, a contractor asking for more than the estimate, a price increase on supplies. Her body treated it like danger anyway. And because the feeling showed up fast, her decisions followed fast. That’s how a habit becomes a trap: you don’t just respond to money - you respond to the emotion money brings up, and then you label the result “my strategy.” Avery would call it “being responsible.” But it was actually a reflex.
When you’re in that reflex, you’re basically training your money habits to fail. You’re teaching your brain that setbacks mean you should override your plan. So tell me - does your money brain do the “panic, fix it now, adjust the plan” dance too?
The Question That Changes Everything: “What Is This Feeling Trying to Tell Me?”
Here’s the provocative question most people never ask themselves when money gets loud: What would I do if I treated this trigger like information instead of a command?
Because the truth is, your triggers aren’t random. They’re emotional alarms. They show you what your mind believes is at stake. Late payments don’t just threaten your cash flow - they threaten your identity (“I’m in control”), your safety (“I might not be okay”), or your future (“If I don’t fix it now, everything collapses”). When you don’t name that, your brain fills in the blanks with urgency. Then urgency becomes permission. Permission becomes a habit. And you end up repeating the same financial mess with a new excuse every time.
Avery did a before-and-after that was so simple it almost felt silly. Before, when a client delayed payment, she’d immediately “patch” the problem - pulling from savings, using credit “just for now,” and then spending the next week trying to catch up. After, she added one step within two minutes of the trigger: she asked herself, “What emotion is driving this?” She’d say it out loud, like a fact. “This is fear.” Or, “This is pressure.” Then she asked the second part: “What does fear want me to do?” The answer was always the same: “Override the plan.” Once she saw that, she could choose differently. Same trigger, different response. Her “fix-it-now” became “check the plan.”
The difference wasn’t that Avery suddenly stopped having problems. Problems still happened. But instead of becoming the person who reacts, she became the person who notices. And when you notice first, you get your plan back.
The Trigger-to-Tool Resilience Plan: From Setback Spiral to Habit Cue
This is the cause-and-effect you’re living in right now - and the alternative you can build.
• When you see a late payment or surprise expense, your body tightens and your mind goes scanning for rescue.
• You feel panic/pressure/urgency (that “don’t wait” feeling).
• So you override your plan - moving money, spending faster, or making a “quick fix” that costs you later.
• Which leads to a setback spiral: you’re behind again, and the next trigger hits even harder because your brain expects chaos.
Now here’s the alternative chain using the Trigger-to-Tool Resilience Plan:
• When the trigger hits, you label it in real time: “This is fear. This is urgency.”
• You feel the emotion fully for a moment - but you don’t obey it. You treat it like a signal, not a supervisor.
• So you reach for your money tool instead of a shortcut. (For Avery, her tool was a pre-written “trigger script” + a one-page transfer rule.)
• Which leads to stability: even if the money problem is real, your habits don’t collapse. You still adjust - but you adjust on purpose, not on impulse.
Avery’s “money tool” wasn’t fancy. It was a rule she posted next to her desk: if a payment is late, she checks the same three things every time (outstanding invoice date, cash buffer, and the agreed minimum operating amount) before moving anything. That’s it. No dramatic heroics. No “let’s see what happens.” The tool interrupts the reflex loop.
Your triggers don’t control your money - your habit cues do.
Rate Yourself: Are Your Triggers Running the Show?
Let’s get honest. Rate yourself from 1-10 (or use yes/no) and don’t overthink it.
• When a money issue pops up, how fast do you start reacting? (1 = I notice and pause, 10 = I act before I even think)
If you’re high, your emotions aren’t just influencing your decisions - they’re driving them. That means you need quicker cues, not “someday changes.”
• How often do you “temporarily” move money from savings or long-term goals? (1 = rarely, 10 = constantly)
If this is frequent, your brain is using urgency as permission. You don’t need more discipline - you need a stronger trigger-to-tool bridge.
• Do you know the exact feeling under your money behavior? (yes/no)
If you can name it (“fear,” “shame,” “pressure”), you can work with it. If you can’t, you’ll keep treating symptoms instead of the signal.
• After a setback, do you return to your plan within 24-48 hours? (1 = yes, 10 = no, I spiral for weeks)
If your return time is long, your trigger isn’t just causing one bad decision - it’s resetting your identity and habits.
Quick interpretation guide:
• Mostly 1-3: You’re already building resilience. Your job is to tighten your cues so you don’t drift.
• Mostly 4-7: You have moments of control. You’re close - your next win is consistency in the first 5 minutes.
• Mostly 8-10: Your reflex is strong. That doesn’t mean you’re broken. It means you need an automated tool - something you can run even when you’re stressed.
Start Building Your Habit Cues Today: The 3-Step Resilience Reset
Ready for something you can actually do immediately? Here’s a fast challenge built for real-life triggers, not “someday” intentions.
The 5-Minute Trigger-to-Tool Reset
• Set a trigger cue on your phone today (2 minutes).
Pick one recurring trigger (late payment, surprise bill, slow sales). Create a note titled: “When this hits, I do this first.”
Difficulty: Easy
• Run the reset for the next money trigger (5 minutes, once).
When the trigger hits, do this exact order:
• Say: “This is (fear/pressure/shame).”
• Then open your note and follow the tool steps inside it.
• Then stop researching for 10 minutes.
Difficulty: Medium
• Schedule a “return to plan” check for later today or tomorrow (10 minutes total).
Set a reminder: “Did I come back to my money plan within 24-48 hours?” Write one sentence about what you did.
Difficulty: Easy
You'll know it's working when...
• You pause for at least one full breath before taking action.
• You use the same tool more than once (not just once as a “good day”).
• After the setback, you’re back on track within 24-48 hours, not stuck in a two-week spiral.
Why This Works (and Why “Just Be Disciplined” Doesn’t)
Here’s the truth: discipline is unreliable when your body is in alarm mode. You can’t out-will a panic response. What you can do is rewire what happens in the first minutes - when your brain is most vulnerable to shortcuts.
The Trigger-to-Tool Resilience Plan works because it stops the hidden story that money triggers tell. Instead of “I need to fix this now” (command), you get “I’m noticing the signal” (information). Instead of “I failed, so I might as well…” you get “I’m in the loop; I have a tool.” You’re not pretending setbacks don’t hurt. You’re building a bridge from hurt to action that doesn’t wreck your future.
Avery’s biggest shift wasn’t a spreadsheet upgrade. It was emotional timing. She stopped treating every money problem like an emergency. She treated it like a cue to run her tool, then adjust with intention. And that’s how resilient habits survive real life - the client delays, the invoice glitches, the surprise bill that shows up like it’s personally targeting your peace.
Your money habits don’t break because you’re not smart - they break because your triggers don’t have a cue.
So when you start turning those triggers into tools, you’ll stop wondering why you “keep doing the same thing.” And you’ll be ready for the next layer: how to build a plan that can handle emotions on purpose - so your progress doesn’t depend on whether the week feels easy.
End of chapter seven. 1 more chapter and about 12,906 words in the full book.
Swipe or use the arrows to turn the page


What's inside: 8 chapters
- 1. Unlearning Money Shame Scripts
- 2. Replacing Scarcity With Abundance Math
- 3. Building a Realistic Budget Without Guilt
- 4. Mastering Money Conversations Without Freezing
- 5. Creating Automatic Savings That Feel Safe
- 6. Breaking the Perfectionism Spend Cycle
- 7. Using Triggers to Build Resilient Money Habits
- 8. Designing a Money Identity You Can Trust
About this book
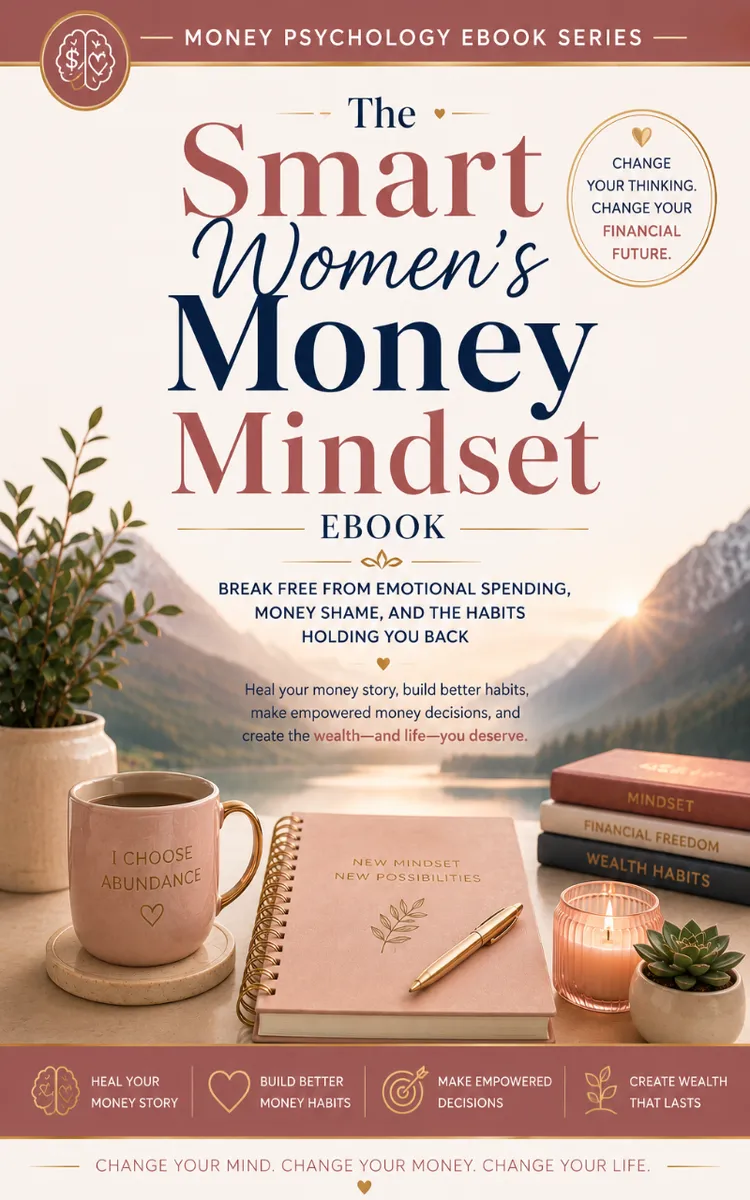
"The Smart Woman's Money Mindset" is a self-help book by Randi Grandison with 8 chapters and approximately 12,906 words. The moment you swipe your card, your body knows before your brain catches up. You feel it as a tight chest, a flash of panic, the thought that you just broke a rule.
This book was created using Inkfluence AI, an AI-powered book generation platform that helps authors write, design, and publish complete books. It was made with the AI Self-Help Book Writer.
Frequently Asked Questions
What is "The Smart Woman's Money Mindset" about?
The moment you swipe your card, your body knows before your brain catches up. You feel it as a tight chest, a flash of panic, the thought that you just broke a rule. Then you doom-scroll deals, overcorrect, or freeze, convinced you are “bad with money.” But what if the real problem is not your math, it is the shame script and scarcity story your mind runs in the background? In The Smart Woman's Money Mindset, you will learn to spot the emotional triggers that hijack your decisions, reset your money identity from “I’m wrong” to “I’m responsible,” and build steadier choices that match your real life. If you want confidence and growth that hold up under pressure, start here.
How many chapters are in "The Smart Woman's Money Mindset"?
The book contains 8 chapters and approximately 12,906 words. Topics covered include Unlearning Money Shame Scripts, Replacing Scarcity With Abundance Math, Building a Realistic Budget Without Guilt, Mastering Money Conversations Without Freezing, and more.
Who wrote "The Smart Woman's Money Mindset"?
This book was written by Randi Grandison and created using Inkfluence AI, an AI book generation platform that helps authors write, design, and publish books.
How can I create a similar self-help book?
You can create your own self-help book using Inkfluence AI. Describe your idea, choose your style, and the AI writes the full book for you. It's free to start.
Write your own self-help book with AI
Describe your idea and Inkfluence writes the whole thing. Free to start.
Start writingCreated with Inkfluence AI


