
Read the first chapter
The whole of chapter one, free. About 8 min. Turn the pages with the arrows, your keyboard, or a swipe.
Chapter 1
Monthly Income Snapshot Checklist
What This Helps You Do
Do you know exactly how much money will enter your home or business this month, and when it will arrive? The Income Ledger Sweep helps you find every income source, confirm each amount, and set a reliable starting balance before planning bills, groceries, debt, or savings.
Use this checklist at the beginning of every month. It works for wages, customer payments, side work, rental income, benefits, refunds, and transfers that support your monthly plan. The goal is not to guess your available money. The goal is to begin with a number you can support with records.
For a home budget, your income may include a paycheck of $2,400, a benefit payment of $600, and $150 from weekend work. For a business, it may include customer invoices, card payments, cash sales, and online deposits. Record each source separately before adding the total.
A confirmed income total gives you a clean starting point. A confirmed starting balance shows what is already available. Together, they help you decide what can safely go toward bills, groceries, debt, and savings.
Before You Start
Set aside 20 to 30 minutes for the first monthly review. A quiet review is better than trying to build the total while paying bills or serving customers. Use the same day each month when possible, such as the first morning after your main payment arrives.
Gather these records before entering any numbers:
• Current bank and credit union balances - Recent pay stubs or payment notices - Business sales reports or invoices - Payment processor reports from Square, Stripe, or PayPal - Cash sale records and deposit slips - Benefit, pension, rental, or interest statements - Transfer records between your own accounts - Last month’s income ledger
Use one page, spreadsheet, or budgeting app for the month. Create these columns:
| Income source | Expected date | Expected amount | Confirmed amount | Account | |---|---:|---:|---:|---| | Main paycheck | May 3 | $2,400 | $2,400 | Checking | | Customer payment | May 8 | $850 | Pending | Business checking | | Side work | May 18 | $150 | $150 | Checking |
Keep expected and confirmed amounts separate. An expected customer payment is not the same as money already received. A scheduled paycheck is not available until the deposit clears. This small distinction prevents you from spending money that has not arrived.
Choose one starting balance date. For example, use the balance shown in your checking account at 8:00 a.m. on the first day of the month. If you use several accounts, list each balance separately. Do not combine them until you have checked for pending payments, holds, or transfers.
Decide how you will treat cash. If cash belongs to the business or household but has not been deposited, record it as cash on hand. Keep it separate from the bank balance. A cash amount of $300 should not be counted as checking money until it reaches the account.
Also identify transfers between your own accounts. Moving $500 from savings to checking does not create $500 of new income. It changes where the money is held. Mark it as a transfer so it does not inflate your monthly income total.
Checklist Items
Complete the Income Ledger Sweep from top to bottom. Start with records, then check deposits, then set the balance. Keep each income source visible until the amount and date are confirmed.
Gather Every Income Source
☐ List every household paycheck expected this month.
☐ List every business customer payment expected this month.
☐ Add side work, freelance jobs, or service calls.
☐ Record benefit, pension, rental, or interest payments.
☐ Add cash sales before subtracting any expenses.
☐ Record refunds only when the money has arrived.
☐ Separate personal income from business income.
☐ Mark irregular income as expected or confirmed.
☐ Include income from every bank account used.
☐ Check last month’s ledger for missed sources.
Review the list against your calendar, email, sales system, and bank activity. A plumber may need to check unpaid service invoices, card deposits, and cash collected at the job. A gym owner may need to check membership drafts, class payments, retail sales, and payment processor deposits. A household may need to check payroll, child support, benefits, and occasional work.
Do not rely on memory for irregular income. A quarterly commission, annual refund, or one-time contract payment is easy to miss because it does not appear every month. Record it only if there is a reasonable basis for expecting it. If the amount is uncertain, enter the lowest amount you can support and label the rest as unconfirmed.
Confirm Expected Deposits
☐ Match each paycheck to its pay stub.
☐ Check scheduled payment dates against bank deposits.
☐ Compare customer invoices with payment records.
☐ Confirm card deposits after processing fees.
☐ Check online payment reports for cleared funds.
☐ Match cash deposits to deposit slips.
☐ Mark unpaid invoices as pending income.
☐ Remove canceled payments from expected totals.
☐ Record partial payments separately from full invoices.
☐ Note payment delays beside affected income.
Use the amount that will actually reach the account. If a customer pays $1,000 and the processor keeps $30, record $970 as the confirmed deposit. Keep the $30 fee in your expense records, but do not count it as available income.
For business income, compare three figures when possible: the invoice amount, the payment received, and the bank deposit. These figures may differ because of taxes, deposits, refunds, processing fees, or partial payments. For example, a $2,500 invoice may produce a $1,000 deposit this month and a $1,500 balance next month. Record only the $1,000 received for this month’s starting plan.
For personal income, check the net pay amount rather than gross pay. Gross pay is before taxes and deductions. Net pay is the amount deposited and available for your plan. If a pay stub shows $3,200 gross pay and $2,460 net pay, use $2,460.
Confirm Money Already Received
☐ Review every income deposit from the current month.
☐ Match deposits to a listed income source.
☐ Investigate unidentified deposits before counting them.
☐ Separate refunds from regular income.
☐ Exclude transfers between your own accounts.
☐ Check deposits still marked as pending.
☐ Record cash on hand in a separate line.
☐ Confirm deposits cleared before planning payments.
☐ Flag reversed or returned deposits.
☐ Update confirmed amounts after each deposit.
An unidentified deposit is not automatically income. It may be a transfer, refund, loan, reimbursement, or correction. Check the bank description and related records before adding it to the income total. This is especially important for businesses receiving deposits from several customers on the same day.
A returned payment also needs attention. If a $600 customer payment appeared and was later reversed, remove it from confirmed income and mark it pending. Your plan should use money that remains available, not money that briefly appeared in the account.
If you receive income in cash, count it and record the date. Keep a separate cash line such as “Cash on hand: $180.” Once you deposit it, reduce the cash line and add the bank deposit. This prevents the same money from being counted twice.
Set the Starting Balance
☐ Record each account’s cleared balance.
☐ Check pending payments before using balances.
☐ Subtract uncleared withdrawals from available money.
☐ Add confirmed cash on hand separately.
☐ Exclude credit card limits from available money.
☐ Exclude expected income from starting balance.
☐ Label restricted business funds clearly.
☐ Confirm transfers have cleared both accounts.
☐ Add account balances only after checking duplicates.
☐ Write the final starting balance on the monthly plan.
Use cleared money as your starting balance. If checking shows $2,100 but a $450 payment is still pending, your usable balance may be closer to $1,650. Check the bank’s available balance and transaction list rather than relying on the current balance alone.
Use this simple calculation:
Starting balance = cleared account balances − pending withdrawals + confirmed cash on hand
For example:
| Item | Amount | |---|---:| | Checking balance | $2,100 | | Savings balance assigned to bills | $500 | | Pending withdrawal | −$450 | | Confirmed cash on hand | $180 | | Starting balance | $2,330 |
Only include savings if you have decided that the money is available for this month’s plan. A tax reserve, payroll reserve, or emergency fund may be in the account but unavailable for regular bills.
For a business, keep restricted funds separate. Sales tax collected from customers may be sitting in checking, but it is not ordinary income available for groceries, tools, or owner spending. Label it clearly and leave it out of the usable starting balance.
Confirm the Monthly Income Total
☐ Add confirmed income by source.
☐ Keep expected income in a separate total.
☐ Exclude account transfers from income.
☐ Deduct processing fees from received deposits.
☐ Separate gross amounts from net amounts.
☐ Check totals against bank activity.
☐ Record the lowest reliable income estimate.
☐ Mark uncertain amounts for later review.
☐ Save the completed ledger with the month.
☐ Write the confirmed total beside the starting balance.
Your monthly plan should show at least two income totals:
• Confirmed income: Money received or firmly scheduled and verified - Expected income: Money possible but not yet confirmed
If confirmed income is $3,050 and expected income is $900, build essential bills around $3,050. Do not assign the $900 to savings or extra debt payments until it arrives. Once received, update the ledger and decide where it belongs.
Finish by writing both numbers at the top of the plan:
Starting balance: $2,330 Confirmed monthly income: $3,050 Expected income: $900
This gives you a clear amount to work with and a clear warning about money that is not yet secure.
Pro Tips
Use one income source name every month. “Main paycheck,” “Shop card deposits,” and “Weekend repair work” are easier to compare than changing labels such as “work money” or “sales.” Consistent names make missed deposits easier to spot and show which sources are growing, slowing, or ending.
Complete a second sweep after the last expected deposit. A five-minute review can catch a late customer payment, returned deposit, or transfer that was counted as income. Update the confirmed total before assigning extra money to savings or debt.
A clean starting balance does more than fill in the first line of a budget. It tells you what is truly available today, while the income ledger shows what may arrive next. When both numbers are accurate, every later decision has a firmer foundation.
End of chapter one. 4 more chapters and about 8,642 words in the full book.
Swipe or use the arrows to turn the page


What's inside: 5 chapters
- 1. Monthly Income Snapshot Checklist
- 2. Bills Due Dates and Amounts Checklist
- 3. Groceries Spending Limit Checklist
- 4. Department Budget Checklist for Your Business
- 5. Savings Buckets for Home and Business Checklist
About this book
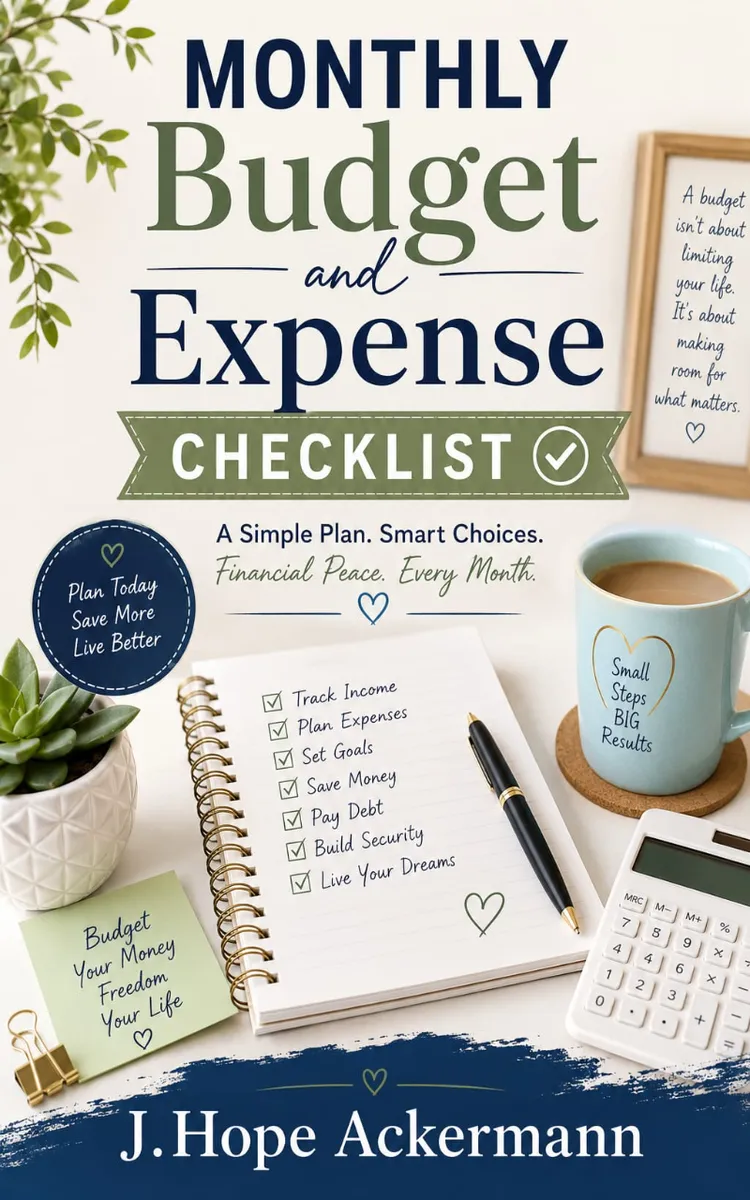
"Monthly Budget & Expense Checklist" is a checklist pack book by J.Hope Ackermann with 5 chapters and approximately 8,642 words. Monthly budgeting and expense tracking checklists for home and business.
This book was created using Inkfluence AI, an AI-powered book generation platform that helps authors write, design, and publish complete books.
Frequently Asked Questions
What is "Monthly Budget & Expense Checklist" about?
Monthly budgeting and expense tracking checklists for home and business
How many chapters are in "Monthly Budget & Expense Checklist"?
The book contains 5 chapters and approximately 8,642 words. Topics covered include Monthly Income Snapshot Checklist, Bills Due Dates and Amounts Checklist, Groceries Spending Limit Checklist, Department Budget Checklist for Your Business, and more.
Who wrote "Monthly Budget & Expense Checklist"?
This book was written by J.Hope Ackermann and created using Inkfluence AI, an AI book generation platform that helps authors write, design, and publish books.
Write your own checklist pack book with AI
Describe your idea and Inkfluence writes the whole thing. Free to start.
Start writingCreated with Inkfluence AI


